Finance
Insights
Finance Insights and Resources
Practical guidance for building the financial function your business needs, from fractional CFOs who've done the work: cash flow, forecasting, raising capital, and the numbers that drive better decisions.
What Is a Financial Controller? What Does a Financial Controller Do?
Money makes the world go ‘round, especially when it comes to running a business. So when your company is growing, it’s wise to invest in a solid financial team who can keep your books in good shape and help you plan for the future.
But sometimes balance sheets, accounts payable, expense reports, and other money-related tasks are more than anyone accountant should have on their plate.
At this point, it may be time to hire a financial controller to take the reins.
But what exactly is a financial controller? And what does a financial controller do? We’ll explain everything you should know about this accounting role, and help you decide if (and when) it’s something your business needs.
WHAT IS A FINANCIAL CONTROLLER?
A financial controller can be the head of the accounting or finance department in the absence of a chief financial officer (CFO). They’re charged with the task of overseeing all financial records, making sure they’re in line with the money flowing in and out of any business.
The controller is a leader who likely manages other accounts and delegates tasks related to taxes, internal spending policies, bank accounts, and more.
Smaller companies may combine the role of the financial controller with the role of CFO, who typically spends more time focusing on financial strategy and raising money for the company.
WHAT DOES A FINANCIAL CONTROLLER DO?
The daily responsibilities of a financial controller differ depending on the company’s size and the nature of the industry. However, there are a few key tasks that most controllers share in any role.
1. Accounting Management
There are many moving parts in a mid- to large-scale accounting department, and a financial controller makes sure all of it runs smoothly. They manage or delegate tasks such as billing, accounts payable, cost accounting, revenue recognition, and more.
2. Financial Forecasting
Financial forecasting is an important part of any successful business, enabling you to plan for the future and anticipate various scenarios based on your strategy The controller helps forecast financials by calculating future revenue and income streams.
3. Internal Controls Management
An organized, effective accounting department should have well-documented policies and workflows for all business processes. The controller also helps develop and record these policies to improve internal controls.
4. Auditing Oversight
Though the controller does not conduct audits, they do work with outside auditors to ensure the process goes smoothly. Think of them as the auditing coordinator. They’ll be there as the knowledgeable go-between and help you better prepare for the auditing process.
5. Cash Flow Management
It’s essential to know where every dollar is going when you’re running a business, and a controller can help you do so by keeping a close eye on your company’s cash flow. They’ll create detailed reports and provide analysis so you can better streamline your money management.
6. Team Leadership
Ultimately, the financial controller is the most senior position in the accounting department, meaning they spend much of their time taking care of leadership tasks, such as hiring new accountants, developing training programs, and overseeing the daily operations of the department.
WHY IS A FINANCIAL CONTROLLER IMPORTANT?
CEOs may get most of the glory, but don’t be fooled—a financial controller is one of the most essential roles in any company. A skilled controller heads up the financial reporting, improves cash flow and budgets, and prepares a company to plan for the future. The best controllers are highly detail-oriented and able to manage and delegate tasks to keep the company’s financials in order as they grow.
WHO DO FINANCIAL CONTROLLERS SERVE?
Financial controllers serve a variety of needs in a wide range of organizations. An eCommerce company might hire a controller to monitor expenses and create an efficient reporting process. A subscription-based company or SaaS company might hire a controller to analyze churn rates or create advanced metrics to boost profits.
DOES YOUR BUSINESS NEED A FINANCIAL CONTROLLER?
From bookkeepers and analysts to payroll clerks and senior accountants, there are many financial roles to fill within the accounting department. So who do financial controllers serve, and does your business need a financial controller?
Here are a few reasons you might benefit from hiring a financial controller.
1. You Need Someone to Oversee Bookkeeping
If you’re an overloaded business owner or CEO who doesn’t have time to oversee bookkeeping, a financial controller is the ideal team member to handle the task. A financial controller can step in where a CFO might to ensure everything is being accurately recorded.
2. You Want a Deep Analysis of Financial Reports
Are you noticing frequent mistakes in your financials? If so, it can be difficult to pinpoint the source of the problem. A financial controller specializes in identifying and resolving the underlying issues in your books before they become a significant threat to the backbone of your business.
3. You’re Ready to Speed Up the Financial Close Process
As your business grows, it’s smart to look more closely at real-time data, meaning you may need to adjust your financial close process from once a year or once a quarter to a monthly basis. Hiring a financial controller can help make this transition go more smoothly by overseeing and streamlining this process.
4. You’re Worried About Financial Security
Security breaches are an increasing concern for most businesses, and the typical bookkeeper or accountant doesn’t have the background to take on this task alone. However, a financial controller specializes in internal controls that will protect sensitive financial data and minimize the chances of fraud.
WHEN IS IT TIME TO HIRE A FINANCIAL CONTROLLER?
You may be interested in hiring a financial controller, but you’re not sure if your business is ready to take this step. Fortunately, you can look to other companies to see when it’s most common to hire a controller.
Typically, companies that have reached at least $1 million in revenue begin to consider hiring a controller and will have certainly done so by the time they’ve reached $10 million in revenue. At this point, the controller will take over the typical tasks of in-depth reporting, handling internal controls, and taking care of the closing process.
If you haven’t hit this stage yet, hiring a full-time controller may not be in your best interest— fortunately, you can outsource your financial controller services to save you money and enjoy the same benefits of an in-house controller.
CONTROLLER VS. CFO: WHICH IS RIGHT FOR YOUR BUSINESS?
Financial controllers and CFOs often have overlapping responsibilities. And as we mentioned before, smaller companies may hire a controller to cover the typical tasks of a CFO. So what are the key differences between these two roles, and which is right for your business?
A controller is usually the best fit for a smaller company needing someone to oversee reports and accounting, while a CFO is ideal for growing companies that are seeking an expert who can weigh in on financial strategy aligned with your business goals.
OUTSOURCE YOUR FINANCIAL CONTROLLER RESPONSIBILITIES TODAY
Want to learn more about how a financial controller or CFO can benefit your company? Contact Ampleo today to find out how outsourcing the task could be the best way to help your business grow.
We specialize in all financial roles, including bookkeeping, financial reporting, forecasting, fundraising, and more.
Our expert team of CFOs and financial controllers will help you reach your goals, establishing a relationship of trust and transparency along the way. We specialize in SaaS accounting, eCommerce financial strategy, and more. Get in touch with us today.

Three Ways You Can Strengthen The Financial Backbone Of Your Business
When you think about what constitutes the financial backbone of your business, what comes to mind? Is it the team? The financial statements? In truth, it’s both of these combined, and more. As a primary driver of performance success, the financial core of a business runs with all the cogs working together in sync. How might you go about improving your financial backbone? Here are three ways you can nail down a strong foundation.
Establish The Right Team
Brigham Young University Rugby head coach David Smyth said concerning his team during the 2014 season,
“We knew we were going to have a solid team collectively this year… but we also knew we were going to lack in some areas up front, so it took a while to figure out the exact combinations and personnel that we were going to have to lean on when the postseason began. But I think once we sorted that out and the players were able to get to know their roles, then we started building and playing some good rugby.”
That year, BYU won the title of Varsity Cup National Champions. Like Coach Smyth, you have the chance to evaluate your team, play to your strengths, and mitigate your weaknesses. Each role in a financial team has a responsibility to cover what the other roles cannot complete as efficiently.
Sometimes, business owners glue themselves to the idea of doing the most without having to build onto their current team, which may likely do more harm than good in the long run. Matching your financial lineup with your growth goals is critical in operating at an efficient level. Where one eCommerce business might be starting out with basic inventory bookkeeping, another business in the same industry might be exploding, and having a small team of accountants won’t cut it for scaling. The second business might be ready for a controller or CFO. Actively assessing your performance levels and goals will help you recognize your needs and evaluate the type of finance professionals you need.
What’s the difference between the levels of financial professionals? While a CFO and controller work together to uphold high standards for financial data and accurate financials, the CFO works closely with you to execute the vision and goals of the company. The controller is just as important for understanding and reporting on the GAAP, accounting, and operational end. Read here for more information on the difference between a CFO and a controller.
Maintain a solid financial reporting structure
This cannot be stressed enough. Maintaining an accurate and timely reporting structure includes ensuring the accuracy of the balance sheet (accounting for assets, liabilities, and equity) and income statement. Having unstructured and cluttered financials bleeds over into the income statement and forecasting levels.
If you feel overwhelmed at the thought of grappling with messy financials, consider taking on outside financial help from an expert. Outsourcing someone who will set up processes in place will significantly cut back on effort on your end and simultaneously improve your financial data.
Keep in mind that having the right KPIs in place for your business model can make all the difference. What might be great metrics for eCommerce may not be as relevant to businesses in the food services industry. Many owners also tend not to see the importance of having the right technology in place for financial operations. Especially without a CFO or controller on board, owners might miss out on certain tools that can automate many financial tasks, such as Quickbooks or NetSuite. Keep an open mind to what might be a good investment in terms of tools and technology to support your finance team.
Long-term and short-term planning
Hopefully at the end of 2020, you sufficiently prepared and planned for a solid Q1 in 2021. Successful entrepreneur Jim Rohn said, “We all need lots of powerful long-range goals to help us past the short-term obstacles.” Long-term and short-term planning work in tandem to help us achieve our overall business goals. The essence of long-and-short-term planning is leveraging your business advantages and KPIs as you align yourself to your overall strategic plan.
Long-term planning may have different meanings for businesses at different growth stages (up to 6 months for startups and 2—3 years for larger businesses). Look to your yearly business strategy as you make plans. How would employee contributions and sales resources add to your growth? What internal or external factors might impact your plans? How will you go about acquiring funding? These questions will be helpful in determining your long-term plans in accordance with your strategy.
Short-term planning primarily addresses potential damaging events and circumstances to the business (think economic strife, cash shortages, or other unforeseen events and expenses). As always, your planning and strategy should be apparent in your financial data. It’s impossible for you to fully predict the waves of economic change on a yearly or quarterly basis, but having a contingency plan for events such as further economic distress and capital raise will serve as an anchor in the survival of your business.
Not to be overlooked in short-and-long term planning is financial modeling. Crucial in understanding timelines and financial performance at any future time period, financial modeling sets the stage and acts as a sandbox for you to identify different results and make adjustments to current operations. It produces insights for current financial planning and helps you identify what obstacles might arise based on current performance. Read here for more information on financial modeling.
These three steps are basic, but they serve as instrumental parts of keeping a well-oiled finance machine. Don’t feel like you have to do it all on your own, however. Getting professional help from an accredited finance expert can shift the weight from you. Improving your team, planning effectively, and reporting accurately will enable you to answer with more confidence when hard times come knocking.

What You Need to Know about Applying for a PPP Loan
Relief is once again on the horizon. The Consolidated Appropriations Act of 2021 (CAA), signed into law on December 27, 2020, approved a third round of the Paid Protection Program (PPP), which includes $284 billion in relief for small businesses.
Whether you are applying for the first time or you are looking at another round of relief, there are some things you should know about where to apply for a PPP Loan . We’ll go over the conditions and guidelines during this third round of funding to help you navigate this process successfully.
Where Is the Best Place to Apply for a PPP Loan?
Banks are often your best bet when it comes to seeking PPP Loans, but other lenders trusted by the U.S. Small Business Association (SBA) are also viable options.
If you want a relatively easy and fast way to apply for a PPP Loan, you should consider applying through your current bank. Loans require a significant amount of time to complete background and identity checks. Working with a familiar bank will expedite the background check process.
Even if you’ve previously applied for a PPP Loan through your bank, there’s nothing wrong with applying again. As long as you’ve operated within the guidelines of the last loan, your bank or another lender likely won’t have a problem with lending to you during this third round of funding.
Which Banks Accept PPP Applications?
Many banks are accepting third-round PPP applications. This includes most national banks like Wells Fargo and JP Morgan Chase and even some regional banks. For example, in Utah, Zions Bank and Rock Canyon Bank currently accept new applicants.
To find out which banks and other lenders are eligible to make PPP Loans, visit the U.S. SBA Lender Match website .
Where Do I Apply for a PPP Loan Online?
If a bank or other lending agent accepts online applications, they will usually inform you of this option on their website. Some lenders won’t give you the option to apply for PPP Loans on their website. Instead, they may require you to fill out an external application form. If that’s the case, you can easily find those forms at the following links to the SBA website:
Who Qualifies for PPP Loans?
PPP Loans are specifically designed with small businesses in mind. To officially qualify, your business must meet certain requirements. If this is your first PPP Loan, you will be eligible if your business meets any of the following criteria:
- Your business was operational before February 15, 2020
- Your business is still open
- You have fewer than 500 employees (or no more than 500 per location if you have multiple places of business)
Can You Get a Second PPP Loan?
The CAA provides two types of PPP Loans during this round: first-draw and second-draw. Simply put, first-draw applicants have never received a PPP Loan, while second-draw are those who received a loan during the last two rounds of funding. So even if you already received a PPP Loan from one of the first two rounds of funding, you can get a second loan
The amount you receive in your second PPP Loan will be substantially less than your first loan. First-draw loans are for companies that have yet to receive any PPP assistance. These companies may receive up to $10 million . Companies that have already received a PPP Loan are limited to an additional $2 million.
If you wish to apply for a second-draw PPP Loan, your business must meet the following criteria:
- You have used all of your first PPP Loan
- Your business was operational before February 15, 2020
- Your business is still open
- You have fewer than 300 employees (or no more than 300 per location if you have multiple places of business)
- Your business saw a 25% or greater decrease in gross revenue in 2020 (when compared to 2019)
What Disqualifies Businesses from PPP Loan Eligibility?
There are certain variables that will disqualify your business from PPP Loan eligibility:
- Your business is publicly traded
- Your business is owned by China by more than 20%
- Your business is a hedge fund or private equity firm
- Your business, or another business that you owned, has defaulted on a loan from the SBA or any other federal agency
- You or your business are bankrupt or in bankruptcy proceedings
- You or a close relative are a key employee for the lender with which you applied for a loan
- An owner of 20% or more of the company has been incarcerated, on probation, on parole, or convicted of a felony within the last year
When Is the Deadline to Submit a PPP Loan Application?
The PPP Loan application deadline is March 31st, but access to funding may run out sooner if federal funds are depleted. This applies to both first- and second-draw applications.
What Are the Guidelines for Using the PPP Loan?
The CAA has placed certain restrictions on how you can use the PPP Loan. For example, the majority of your loan (60%) must be used to cover payroll expenses. Other approved uses of the loan include coverage of:
- Rent, mortgage interest, and utilities at your place of business
- Operations expenses, such as business software, cloud computing services, product/service delivery, supply tracking, payroll processing, etc.
- Property damage costs that are not covered by insurance policies
- Supplier costs that are essential to business operations
- Worker protection expenses, including any expenditures required for compliance with the CDC, OSHA, HHS, or any other state or local government
Can You Seek Loan Forgiveness?
The PPP Loan is unique—if you follow all of the guidelines listed above, then you can seek forgiveness on your PPP Loan. But if you fail to comply with even one of the guidelines, you will have to pay the loan back in installments.
There are two different loan forgiveness applications you can fill out. The first is the Paycheck Protection Program Loan Forgiveness Application . Your business will likely use this one.
The second application is the Paycheck Protection Program EZ Loan Forgiveness Application . This form was introduced during the second round of PPP funding and is half the length of the previous application. You can apply for loan forgiveness with the EZ application only if your business meets at least one of the following criteria:
- You are a self-employed individual, independent contractor, or sole proprietor who had no employees at the time you submitted the PPP Loan application
- You did not reduce the annual salary of any employee by more than 25% during their covered period when compared to the first quarter of 2020 (January 1 – March 31)
In these cases, the term “employees” refers to individuals who did not receive wages or a salary of more than $100,000 a year during 2019.
Balance Your Budget with Ampleo
If you want assurance that you will stay within the parameters of the PPP Loan guidelines, you must balance your budget and ensure financial accuracy. A solid budget will help you determine exactly how much assistance you need to request and where you will apply the funds you receive. Consider hiring a financial expert to help you if you’re feeling overwhelmed. Our financial experts offer a full range of financial services, including CFOs, accountants, bookkeepers, and controllers. If you want to ensure that you can apply for PPP Loan forgiveness, call Ampleo today to get your budget in order.

Eight Steps For Strengthening An Inclusive Workplace
Setting a diverse workforce up for success requires a commitment to the practices of inclusion. While this concept can feel overwhelming in many ways, there are very tangible and tactical actions that individuals and organizations can take to drive a culture of belonging… a culture where diverse contributors have equal opportunity and impact. Meetings are a space where some simple steps can be taken to drive this impact effectively, by actively and intentionally giving individuals opportunities to contribute, share, and be involved in the conversation.
A truly inclusive environment that fosters a sense of psychological safety and belonging has been shown to improve business performance and organizational effectiveness across the board. Organizations with inclusive cultures are twice as likely to exceed financial goals and 8x more likely to achieve better business outcomes (Bourke, 2016). It has also been shown in a Glassdoor Diversity Hiring Survey that 67% of job seekers indicated that being part of a diverse and inclusive company was important to them when evaluating job offers.
- Review your list of attendees. Are you missing people who represent diverse or dissenting points of view?
- Set the stage for inclusion. Send a pre-meeting email to attendees to invite them to come ready to share. Include an agenda and any prompts that will allow them to prepare for the dialogue.
- Set clear ground rules at the start of the meeting and stick to them. When inclusive meeting conduct is codified, it puts offenders on notice and makes everyone aware of their rights and responsibilities.
- Model the behavior you expect to see from others.
- When a big question arises, have the group take a few minutes to put their ideas on paper, then go around and have everyone share. This gives fewer vocal participants time to gather their thoughts and ensures that their voices will be heard.
- Watch closely for dominators and interrupters. If someone tries to control the dialogue, interject and redirect the conversation back to the broader group.
- In virtual meetings, there is often an option to allow for text-based contributions to the conversation.
- Follow up after the meeting. Thank participants and ask for their feedback (overall effectiveness and inclusivity).
The journey to creating an inclusive workplace is worthwhile. As business leaders, if we’re able to successfully create spaces where our employees feel valued and appreciated we will reap the benefits tenfold.
Two Elemental Considerations in Scaling Your Software Company
The first task of any business is to get out a minimum viable product, leading toward product market fit. Once achieved, we often see companies race to sell, sell, sell. This can sometimes be the right answer, but preparing your business to scale means more than just finding a fit and then turning on an efficient sales engine.
Scaling can mean two things:
- The ability to keep up with growth operationally
- The ability to expand your margins while growing
Keeping Up Operationally
Scaling operationally means growing—sometimes very quickly—without negatively impacting other areas of the business. For example, employee turnover can rise as demand grows for individuals or as roles fall out of alignment; difficulties can arise quickly in finding and developing leadership; product businesses can fall behind demand and struggle with production at increasing volumes.
Potential problems are endless and often unpredictable. You don’t need a list of answers to all possible problems to have the confidence you need to face challenges; what you might need is a personal system by which to work through them.
In my experience, what works for me is establishing a regular thinking space by dedicating every Thursday morning to what I call “thinking time”. Clearing away the noise once a week gives me the room I need to get proper perspective and tackle some of my most difficult challenges. Through my experience with this, I’ve gained the confidence to tackle any problems that arise. It’s this space that enables me to find the answers to new challenges.
Information is the lifeblood of making good decisions in your business. Scaling operationally means not letting key elements of running the business fall behind. One frequently overlooked crucial element is your systems and data. Data can rapidly grow overwhelming to review, or can get dirty and hard to trust. It’s so much easier to plan ahead here than it is to try to clean up historical information. Businesses often have their own unique data sources. An early partnership with someone to help you manage your systems and data, or dedicating a resource to it internally will pay long and big dividends.
Expanding Margins
When we take a zoomed-out view, we see that software companies typically go through similar stages. Once MVP (minimum viable product) and MVI (minimum viable infrastructure) are achieved, there is a period of rationalization that occurs where enabling revenues to catch up to expenses is elemental to a strong growth strategy.
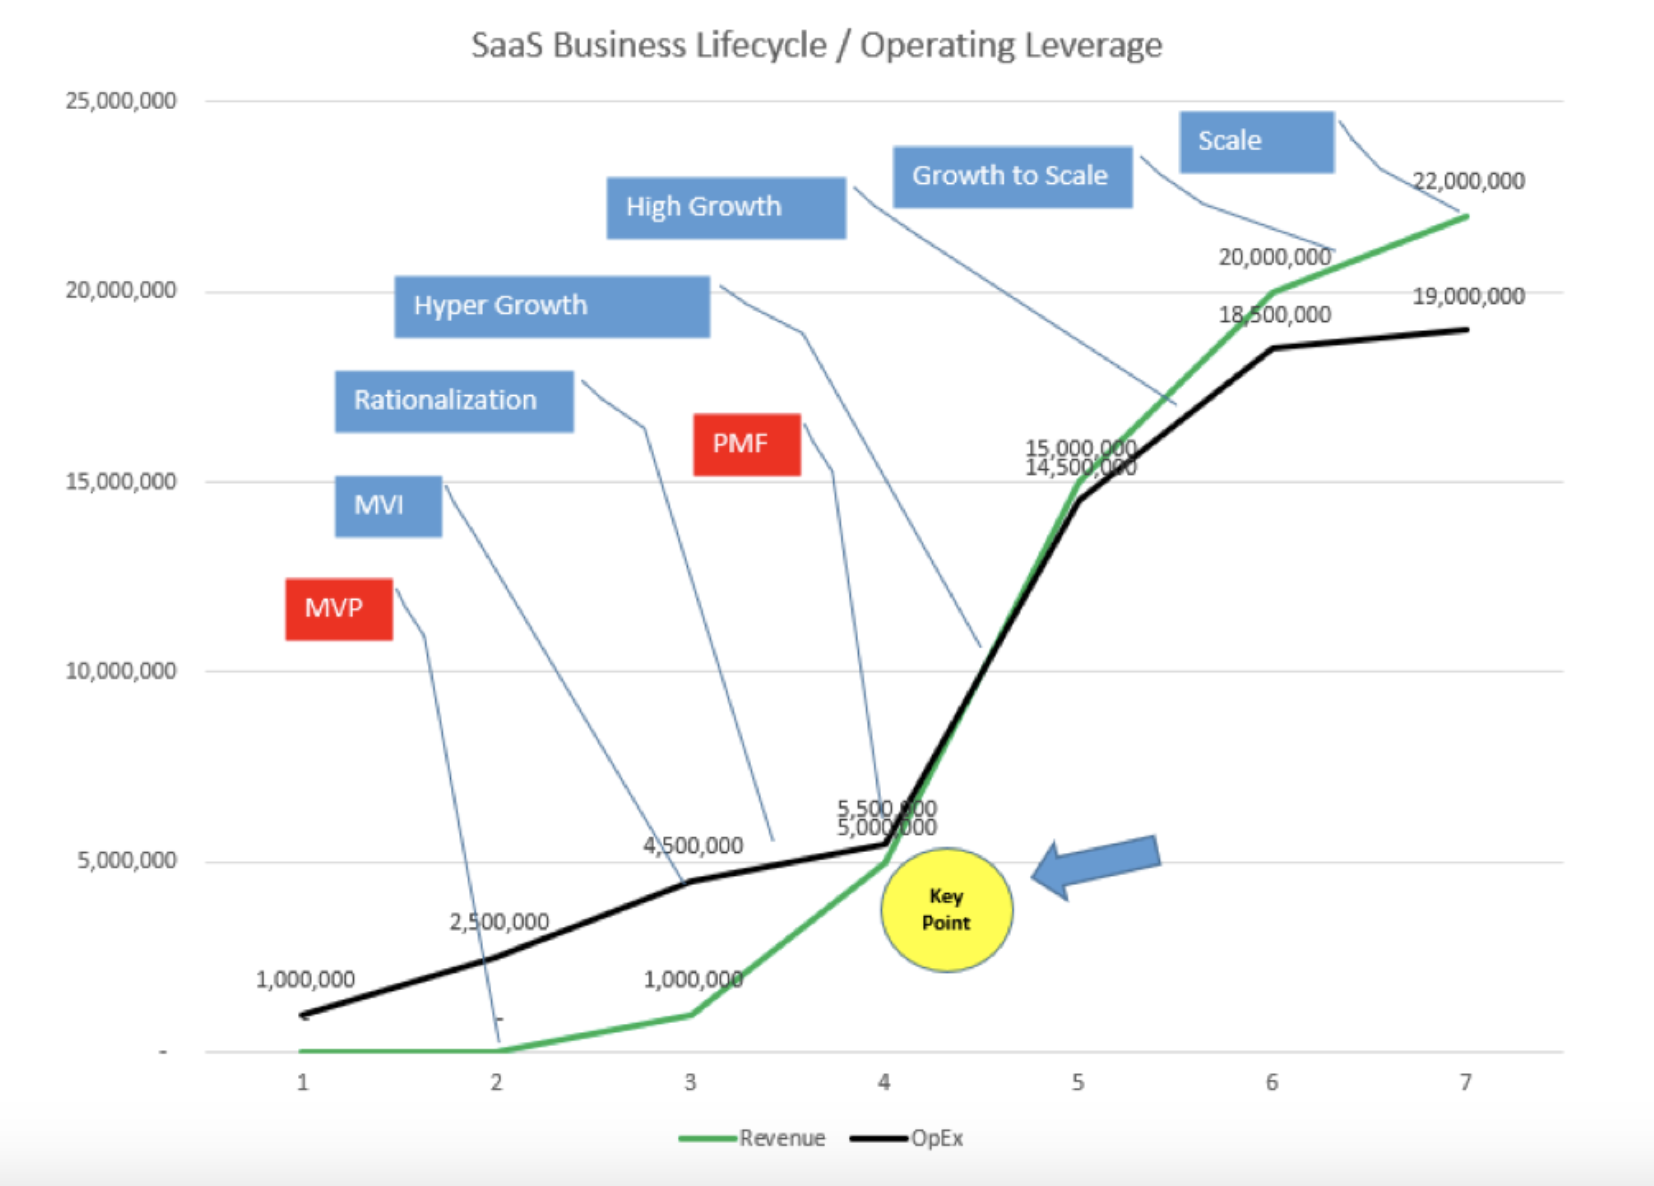
The essence of scaling margins reduces down to growing revenue faster than costs are being added. It’s about adding sales as efficiently as possible and finding leverage in the other business costs. This includes all selling and marketing costs and the costs of delivering your products. If you aren’t fully aware of these unit economics in your business, become aware. Understanding and expanding your unit economics is the ultimate key to profitable growth and scaling.
Much has been said about expanding sales profitably. Most software companies focus on CAC (Cost to Acquire Customer), and rightly so. Comparing the cost to acquire a customer against the margin you’ll receive from that customer is at the foundation of profitable growth.
However, not all software companies are created equal. Those with lower gross margins than others need to be fully aware of the other incremental costs of adding revenue—otherwise, cash margins will never expand.
There are myriads of resources for digging into challenges around scaling. Some of my favorites are David Skoks ForEntrepreneurs.com which has some great material on scaling challenges and the Openview Venture Partners page called: Measures of Success: SaaS Metrics & Benchmarks Resource Guide which is a living document loaded with the latest and best content for SaaS companies.
CEOs: This is what you should look for in your CFO
When you’re kept up at night mulling over critical decisions for your company, who are you looking to for trustworthy insights? Business leaders seek counterparts who will complement their own talent and leadership styles to further the goals of the company. Perhaps you’re in the active hiring stage for a new CFO, or maybe you’re already working with your CFO and you want to know if they’re up to par with industry standards. Although CEOs may have different priorities for characteristics they look for in a CFO, there are certain elements that are must-haves for any CFO, regardless of industry or business.
This article covers the essentials for what CEOs should expect from their financial leaders. We pulled our insights from a survey of 130 Ampleo clients on technical skills and characteristics they value the most in their CFO.
Technical Skill
1. Maintaining the financial accuracy that keeps the business running
The number one priority for a CFO is to provide accurate, reliable, and timely financial statements. Always. This most fundamental responsibility provides the groundwork for the integrity of business decisions. This also happens to be number one on our survey for technical qualities CEOs value most in their CFO. If a CFO isn’t delivering on this fundamental task, and if he or she fails to hold the team accountable to do so, credibility is gone.
You may know how it feels when a CFO doesn’t fulfill these basic duties—it’s discouraging and leaves a very real impact on the business. In a global survey of 1000+ C-suite executives, Blackline shares that approximately 70% of business leaders and finance professionals have made at least one business decision from unreliable financials. With this sobering statistic, it’s no surprise that CEOs must maintain a careful approach to selecting and partnering with their CFO.
The second most important technical quality from our survey is the ability to create a solid cash flow forecast. Business owners often underestimate the enabling power of having clear insight into their cash flow. Too many CEOs are unwittingly hamstrung when they receive only the limited views that come from information within the income statement. A CFO who understands their responsibility to provide insight into cash flow and who communicates its importance to company leadership is one who demonstrates the strategic thinking that makes all the difference in building a successful business.
2. Strategy: the ability to interpret and provide insights
One of your focus areas is to meet your goals for business growth. So, how is your CFO going to help you with these efforts? Once CFOs competently execute on maintaining financial accuracy, they should shift to more strategic initiatives.
A 2017 McKinsay article states, “Eighteen percent of CFOs say that, in the past year, they have created the most value for their companies through their traditional finance work. But others are most likely to cite strategic leadership (22 percent) as the area where they’ve created the most value.” Once financial integrity is established, the next logical duty of a CFO would be to aid you in the scaling and expansion of the business.
A CFO’s role in this area is critical, as they have the power to combine accurate data with robust insights. Beyond short-term responsibilities, a CFO should be forward-thinking and should readily consider the long-term consequences of today’s decisions. Considering the current economic environment, a CFO’s role is developing in that they are expected to take on more of a proactive leadership role while addressing the challenge of keeping the financials accurate and insightful during volatile times.
So, you have some awesome data. Your finance team is working like cogs in perfect synch…. Now what? How do you know if you have a strategic CFO? One indicator is if they ask questions about the trajectory of the company, current constraints, and concerns that you might have. Another indicator is if he or she brings different strategies to the table, analyzes them with you, and visualizes potential impacts on the business.
Key character traits
Technical skills and strategic abilities are vital—however, many business owners forget to take into account what character traits they value in their CFOs.
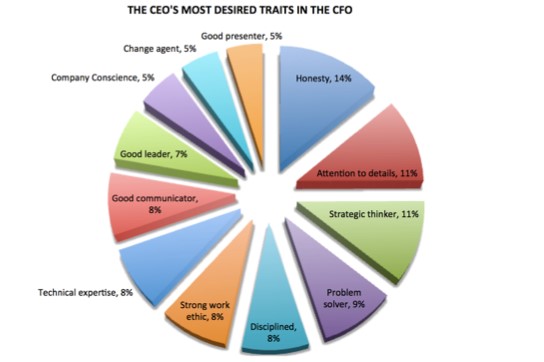
The chart above represents the results of our 130 CEO clients on what character traits they value (based on a forced ranking). The top result is honesty, followed by attention to detail and strategic thinking.
1. Honesty
We all know our fair share of anecdotes about dishonesty in the workplace. Ethics and honesty both fall into the category of answering the questions, “Can I trust you? Can I rely on you to act as the stabilizer of my business?” A CFO with a brilliant mind can work wonders—but will all of that go down the drain when you find out that he or she is being dishonest? Integrity in leadership sets the tone for behavior in the rest of the organization. A CFO’s reputation of honesty cascades down to the rest of the team.
2. Strategic thinking and attention to detail
Whether coming up with new automation for streamlining financial processes or examining data from a different perspective, a strategically minded CFO makes a world of difference. A strategic CFO has the vision to identify external and internal disruptors in the market down the road. Attention to detail and presence of mind goes hand-in-hand with strategic thinking. The ability to observe certain trends in data or in the marketplace—combined with proper team management—can foster an internal environment of accountability. A detail-oriented CFO takes what they know about the current strategy, evaluates the components, and translates them to operational priorities for the business.
You’re entitled to your preferences on what to look for in a CFO. However, make sure that your CFO meets the essentials. The CFO acts as a navigator in turbulent waters, and serves as an anchor, providing data-backed recommendations for the business. In either selecting a CFO or working with your current CFO, keep an eye out for these qualities. Having a CFO that meets these can bolster your confidence and build a sure foundation of information from which to propel your business into profitable and healthy growth.
Seeing Your Strategy in Your Numbers
If you have a business strategy, it should be visible in your financials. Point blank. This may seem like an obvious claim, but surprisingly, not all business owners come to recognize this.
According to Michael Porter, “Strategy explains how an organization, faced with competition, will achieve superior performance”. This superior performance referred to by Porter is best measured by ROIC (Return On Invested Capital).
Because of the long investment cycle for software and recurring revenue models, ROIC may not be measurable until the business approaches to scale. This can take over a decade for most software businesses.5 Key Metrics to ‘See’ if Your Strategy is Working
What are the key metrics you can look at now to ensure that in the end you achieve ‘superior performance’ and know if you do indeed have a tangible strategy that is visible in your numbers? There are five key metrics that will help you see if your strategy is paying off:- Lifetime Development Ratio (LDR)
- ARR Payback
- Net Revenue Retention (NRR)
- Coverage Ratio
- Operating Leverage
Lifetime Development Ratio (LDR)
The Lifetime Development Ratio is calculated by dividing ARR by all the money spent on development costs (including maintenance) over the life of the product. For a subscription software business model to eventually reach scale economics (i.e., generating a 15-20+% operating profit), the development costs need to settle in at around 20-30% of ARR while growth is high and 10-15% of ARR once close to scale. In terms of the LDR ratio, this means that you should be looking to achieve 2.00 or higher in your current budget and be scaling toward an LDR of 2.00 to 3.00. If your LDR is less than 2.00, consider asking yourself the following:- Is the product aligned with what the market needs (product market fit is off)?
- Are the marketing and sales efforts identifying the right customers and are they effective at conveying value?
- Is the development team efficient at building value in creating products and features?
ARR Payback
There are several ways to calculate this ratio, but the generally preferred method is to look at a 12-month rolling new booking vs. a 12-month rolling sales and marketing. I prefer this method because it takes out timing and seasonality issues and shows if the number is improving over time without the noise. The target ratio for this metric is somewhere between 9-15 months of payback.Net Revenue Retention (NRR)
This metric can give significant insight if you divide your clients into ‘strategic’ vs ‘non-strategic’. If you truly have a strategy where you have identified a specific customer set and have aligned your operations to create value specific to that customer set then you should see a significant difference between strategic and non-strategic in the NRR ratio. Strategic clients should clearly feel the value and be willing to pay more and ramp while non-strategic customers will not feel that value, resulting in lower growth and much higher churn. If non-strategic customers are behaving the same as strategic customers, then you will most likely have not customized and focused on your software.Coverage Ratio
The coverage ratio is calculated by dividing the ARR run rate by the OpEx run rate (excluding cost of services). Excluding cost of sales enables companies to benchmark on both an infrastructure level and on a total spend level. Once a company has achieved MVP it should focus on improving the Net Coverage Ratio by rationalizing the business. A business is ‘rationalized’ once revenue can cover operating expenses. A rationalized business can still grow faster than its internal growth rate (IGR = the rate of growth the business could sustain without external financing) by raising funds via debt or equity. If the ARR payback is healthy (between 9-12 months) then the temporary drop in coverage will be replaced within the funding cycle. The combination of investment funding with client funding via prepayment on subscriptions enables a software subscription model to continue to grow rapidly without creating a significant gap in funding and can switch toward profitability at any time. A Gross Coverage Ratio would be the target ratio that would cover not only full spend (including cost of sales) but the target profit margin as well. By using this ratio you can determine how fast infrastructure costs should be growing to maintain a 1.00 ratio and gradually work towards a 1.25-1.70 ratio when you are fully at scale.Operating Leverage
Operating Leverage is calculated by dividing the ARR growth rate by the OpEx Run Rate growth rate. This metric is used to measure leverage and to monitor if the revenue is growing faster than the overall cost structure. There is no ‘right’ ratio, but generally, once MVP has been achieved then revenue should always grow faster than operations until the business reaches scale. This means that the operating leverage ratio should be greater than 1.00 until the business reaches scale.Summary
Once again, if a business has a strategy and an integrated operating plan, then it should be ‘visible’ in the numbers. The best measure of superior performance – which is the objective of having a strategy – is ROIC. The long-term nature of a software business makes it difficult to measure ROIC until the business reaches scale. This long-term nature does not mean a company has to wait and see if it was successful. Monitoring and testing the strategy by using these five key metrics can enable a management team to ensure that the investment is being managed effectively and that its strategy is working to create value for both customers and investors.
3 Ways to Develop a Culture of Accountability
If you’re a business owner, you know the feeling of balancing the world on your plate. Your main priority is to make your business succeed, and your hope is that you build out a high-performing team that delivers success. You may have hired the most qualified employees, but how are you ensuring that they deliver?
You might want to consider assessing your internal culture of accountability. From a financial perspective, accountability directly corresponds to accuracy and trust within a team. This holds true for the rest of the business. As a leader, you have a direct responsibility to develop and maintain this culture.
Oftentimes, the term “accountability” has a negative connotation in the workplace. Employees might associate the word with punishment, slave driver-type management, or tattling. However, at its core, accountability is a way of uniting employees to achieve the performance goals of the team (and ultimately, the company).
Why is Accountability so important?
To illustrate the importance of accountability, it might help to look at a few examples:
Picture this scenario.
An accountant in a medium-sized SaaS company has a clear understanding of her role, which is to provide accurate books and month-end closures. The accountant reports directly to the controller and plans ahead to prepare correct reports. She double-checks numbers well in advance. The controller follows up regularly for timely reports. Both feel united in purpose and efforts. The team works like a well-oiled machine, and trust abounds.
Now let’s look at another case.
A recruiting team at a large retail company has a deadline coming up to hire five new marketing employees. The CEO of the company has not consistently implemented or defined the company values and guidelines; therefore, many of the recruiting team members struggle with complying to guidelines and regulations. The lack of clarity causes a rift between co-workers, and employees vocally express their job frustrations. It’s an “every man for himself” mindset. The recruiting team is barely meeting goals.
We notice a stark contrast between the dynamics of these two teams. Where the finance team feels united and confident, the recruiting team feels frustrated and unmotivated. Imagine the difference in performance and bottom line for these two teams.
Let’s circle back to the question of why accountability is so vital. The simple answer is that accountability facilitates trust, productivity, and achievement of company goals. Employees may have different ideas of what great performance looks like, or what they are responsible for. Leaders are responsible for setting expectations, communicating with their team, and assessing performance. Taking certain actions can be the impetus for implementing a solid culture of accountability.
1. Set clear expectations and objectives.
In 2014, Partners In Leadership released a large-scale scientific study on accountability in the workplace, in which they examined more than 40,000 individuals in organizations over the course of three years.
A sizable 85% of participants stated that they weren’t sure of their organization’s objectives. This ambiguity ultimately trickles down to objectives on a team level. As a decision maker, it’s time for you to take ownership in setting organizational objectives. Start with your direct team, then make sure your objectives are cascaded down to each level of the organization.
SMART goals aren’t a bad place to start. Start with the organizational goals, and train your team on goal-setting and what it means to be accountable. Then do the work to engrain this in your company culture. It may seem like a giant undertaking to have to set these goals in addition to performing your other essential duties. However, understand that culture isn’t established overnight.
Don’t hold back asking for feedback when creating your objectives. Goal-setting can very much be a team effort and mutual agreement on where you want to add an element of personal investment with employees. Be specific in your goal measurement.
Additionally, make sure each employee knows their place in the company- in other words, make sure they have a clear understanding of their jobs and what work is expected of them. Job ambiguity majorly impacts frustration levels and job satisfaction in the workplace, especially for employees who feel unsure if they are doing too much or too little. Lay out clear and realistic expectations for each role, and help employees understand why these expectations are important.
2. Communicate, communicate, communicate.
What’s the purpose of setting goals if you don’t follow through with your team? A Gallup study found that 47% of employees reported getting feedback from management “a few times or less” in the past year. Imagine the increased motivation if employees received positive, encouraging feedback. In the same vein, if employees get feedback on poor performance, imagine their motivation to improve.
Good communication is vital in keeping your team motivated and aligned with goals. This includes providing and receiving feedback, setting up regular reporting, and scheduling check-ins. However, be careful not to confuse good communication and micromanagement. A level of trust must be present between you and your team to ensure that you give each other enough room to deliver.
Well-timed follow-ups can help you avoid making your team members feel as though you’re breathing down their necks. Check-ins can consist of simple questions like “how are you doing?” or “Any concerns with the team?”. These can elicit a short “everything’s great!” or open up a deeper conversation. Shared progress reports are a great way for everyone to view the team’s entire progress collectively and to encourage further team communication.
Team meetings should create opportunities to review goals and track progress, with each individual reporting their individual progress and contribution. Individual reports encourage self-accountability and keep finger-pointing in check.
3. Assess Engagement and Motivation.
At some point, all employees experience decreased levels of engagement or performance. Some employees will continue poor performance, even with a solid system of accountability. Don’t hold back on addressing poor performers as soon as you identify them. Their performance might have a significant impact on the rest of the team.
One-on-ones might be helpful for you to address the issue. Figure out why the employee is performing the way they are. Find the root of the problem, and then apply your leadership skills, remembering to utilize compassion. Assumptions can be the death of us, so don’t venture to make assumptions about employee situations. They may be going through circumstances beyond your knowledge. Start by asking questions about their performance. “You haven’t been reporting X and Y. How are you feeling about the project? What challenges are you experiencing?”
This is where you’ll apply the right leadership style to match the situation. Sometimes managers fear coming across as confrontational or fear that they will damage their social relationships with their colleagues. It’s natural to want people to like us and avoid any actions that may be perceived as aggressive. However, leaders should understand the potential long-term setbacks that result from holding back feedback.
As the aligner, you set the tone for shaping the entire culture of accountability in your business. Remember that accountability doesn’t mean slave driving. The entire purpose of having an accountability-focused work culture is to achieve and build the overall productivity and happiness of the company. Be diligent in your implementation. If done correctly, developing a culture of accountability has the potential to make a significant positive impact on your employees and on your bottom line.
Why You Should Hire an Outsourced CFO
The Chief Financial Officer (CFO) is a key influencer on a business’s success. From startup to enterprise, every business benefits from a strategic CFO. Though different companies have different needs, a good CFO can help make the difference between a successful year and an unsuccessful one.
However, contrary to tradition and popular belief, not every business needs a full-time CFO. Here’s why you should consider an outsourced CFO for your company .
What is an Outsourced CFO?
An outsourced CFO is a financial expert who steps into the role of CFO at a business in a variety of capacities. Outsourced CFOs can be hired in the interim, acting as Full Time CFO until the business is able to hire one. CFOs can also be outsourced on a project, part time, or full time basis, hired to perform one specific task, or to fully command the finance and accounting functions of the business. They can consult, create financial strategies, and effect positive change just as well as a full time CFO, but on a pay for play basis.
In short, an outsourced CFO is your business’ financial expert — on your terms. Outsourced CFOs usually work on an hourly basis, meaning that you only pay for what you use. Fixed fees are also a great option for businesses needing assistance with specific projects. An outsourced CFO adapts and changes depending on the needs of the client.
What Skills Should a CFO Have?
CFOs provide a valuable service, so let’s look at what their skillset should look like.
- Problem Solving and Decision Making. CFOs are faced with big decisions that can drastically affect the trajectory and success of a company. They are faced with unique problems and situations for which there is no easy solution. CFOs are responsible for analyzing the information they have and then creating a solution.
- Data Analysis and Expertise with Big Data . CFOs have to understand what is and isn’t working within their company and their industry. The best place for them to gain that knowledge is through analytics from within and without the company. CFOs should be able to interpret and find meaning in the data they gather. By better understanding what is happening around them, they will be able to provide a better direction for the company and better manage risk.
- Management and Leadership. CFO responsibilities consist of much more than those of an accountant. They are a key part of the leadership in a company and have to be skilled at managing the numbers and managing people. This will help them make better decisions and help their company become more profitable.
- Innovation with Technology. What worked a few years ago can be outdated and useless, and a good CFO should know that. They should have the skills to find, understand, and see the value of new technology. They should feel comfortable being the champion for a digital transformation and drive digitization.
- Flexibility. A good CFO should be comfortable wearing many hats and helping throughout the entire organization of a company. While they don’t have to be an expert in every field, they should feel comfortable working alongside the rest of the leadership team and providing valuable perspectives based on analytics and research.
- Finance and Accounting. While CFO duties and responsibilities are numerous, CFOs are still expected to be skilled at a business’s finance and accounting functions.
What Do CFOs Care About?
The responsibilities of a CFO are to minimize risk, ensure compliance, and protect assets. Therefore, it’s up to a CFO to:
- Hire and retain a strong financial team.
- Manage costs.
- Use big data to guide decisions.
They drive financial intelligence, which makes them responsible for championing more efficient processes and adopting advancements that will directly benefit their company.
CFOs have become more than number crunchers and are more than promoted controllers. While they are still connected to figures and research, CFOs interpret and use that data to drive the strategic direction and success of their company. They care about basic accounting aspects like the annual budget and cash flow, but they also focus on dynamic strategic decisions and investments. A good CFO cares about influencing operational decisions in marketing and strategy with high-quality information to back their decisions.
How Does a CFO Add Value to a Company?
In the past, a CFO was one step above an accountant. However, times have changed, and a CFO’s role has grown. Now they are still responsible for overseeing accounting and the bottom line, but they are also expected to keep an eye on the future. They are responsible for preparing the organization for what is coming (both the good and the bad) while improving cash flow and profitability.
Cash is the lifeblood of any company, and CFOs are responsible for helping the company get the most out of every dollar. CFOs can:
- Drive financial strategy.
- Create financial forecasting.
- Be a strategic partner for each department.
- Improve cash flow.
- Establish financial visibility.
- Optimize and analyze product lines.
- Increase profit margins.
- Implement an effective cash management system.
- Prepare for a transition of ownership.
- Direct changes in operations to increase productivity.
- Communicate with all stakeholders.
- Facilitate analytics.
Why Hire an Outsourced CFO?
Hiring a CFO is a monstrous task. The implications of choosing the right candidate that fits within budget constraints and company culture can mean lots of time and energy spent reviewing resumes and interviewing. Choosing an outsourced CFO may be right for your business if:
You want to hire an expert but can’t afford the salary.
Outsourced CFOs are experts with proven success at many different companies. You’ll get access to their tried-and-true ideas, without having to pay salary or benefits. Just pay for the time you need, when you need it.
You only need a few hours a month.
Outsourced CFOs can work on a part-time or project basis, which means no more paying for unused hours. Even better, outsourced CFOs are experts and have worked as CFOs for several different companies, so they’ll likely be able to get the job done in even less time than someone with less experience.
You’re looking to hire a full-time CFO, but need help in the meantime.
Outsourced CFOs can pinch hit for a short period of time, keeping the financials up to date, assisting with planning and modeling, and managing the financial function so you’re free to focus on choosing the right candidate. Even better, they’ll help make the transition even smoother once you’ve found the right person for the job.
You’re worried about choosing the wrong candidate.
A good hire means more than finding the right expertise to get the job done. Oftentimes cultural fit and personality can make or break an employee relationship, especially at the executive level. Outsourced CFOs work differently than internal hires and mitigate the risk of hiring the wrong person. Take an outsourced CFO for a test drive on a project or two before bringing them in full-time. If it doesn’t work out, no harm, no foul.
Outsourced CFO for Every Stage of Business
Because of the flexible nature of outsourced CFOs, businesses of all sizes can benefit from their services.
Startup
Startups often don’t need a full-time CFO, so paying $300,000+/year plus benefits is unnecessary. Budget constraints can also limit companies from hiring an experienced CFO, so many startups hire connections that may not actually have the experience they need. An outsourced CFO is ideal for startups to stay under budget and get the strategy and expertise they need to grow.
Growth Stage
As a company grows, its needs can change dramatically. Accurate financial modeling and planning is paramount to successful growth. Because needs may differ from month to month, an outsourced CFO is a good option, taking on projects and tasks as needed. It’s a win-win — the company saves money on unused hours and gets an experienced professional to get the job done.
Enterprise
Large businesses usually have more full-time needs than smaller businesses. In this dynamic, outsourced CFOs can plug into organizations as consultants on a short-term basis, or can even fill CFO needs on a fixed-term basis. For example, if a company loses its CFO, its need for strategic analysis and planning doesn’t go away during the hiring process. Yet, hiring a good CFO can take time. Outsourced CFOs can step in during the interim and help make the transition easier for both the company and the new CFO.
When to Bring a CFO On
One of the benefits of outsourcing the CFO position is that you don’t have to wait until your organization is large enough to require full-time CFO responsibilities. Outsourced CFOs are scalable in a way that a full-time hire isn’t. That being said, there are certain times when the input of a CFO becomes particularly valuable, such as:
- Preparing for Growth. CFOs provide a big-picture perspective that can be extremely helpful when your organization is preparing to expand. Since one of the responsibilities of a CFO is to plan for the future, they can help you avoid pitfalls and better plan for success.
- Raising Capital. The very presence of a CFO can help provide credibility to potential vendors and lenders. In addition, a CFO can help you determine how much capital you need and what sort of debt you can afford to take on.
- During Audits. Nobody likes an audit—but no one knows the books and your financial situation like your CFO. Although they provide value daily, a quality CFO is particularly essential during audits.
- Fine-Tuning Strategy. Any accountant can tell you what the ledgers say, but a CFO is a member of the leadership team that can help guide the direction of any company. They’re likely to provide a valuable perspective distinct from the other executives at your organization.
Outsource Your CFO Through Ampleo
As your business looks to hire a CFO, consider hiring an Outsourced CFO, instead of a full-time CFO. You’ll get best-of-breed financial expertise and see the same results for a fraction of the cost of a full-time CFO.
Not sure what your business needs? Ampleo offers highly skilled CFOs ready to tackle your business’s unique challenges. Contact us for a free consultation.
Convertible Notes, SAFE Notes, and Revenue-Based Financing Explained (In Simple Language)
We frequently are asked about the merits of various methods of business funding. When CEOs are curious about non-equity capital, those discussions inevitably come around to the ideas of convertible notes, SAFE notes, and Revenue-based financing. And sometimes I get blank stares when walking through the concepts of conversion, discounts, caps, etc. I’ve even heard, “Ok Dave, whatever, I trust you”, which isn’t the best answer. We’d rather that entrepreneurs understand exactly what they’re getting into.
This article by TIMIA capital does a nice job explaining the pros and cons of these three types of capital – Convertible Notes, SAFE notes, and Revenue lending.
However, I think entrepreneurs that find themselves with circumstances that fit funding of this nature should also consider the other various types of venture lending which are growing in popularity. Fundera summarizes the pros and cons of venture debt here.
I can’t stress enough that, when looking at the various options for funding, you should find capable advisers who have experience with raising capital from these sources. Good advice, specific to your circumstances, can help you avoid significant challenges down the road.
1 Question CEOs Should Ask Before Starting a Business
The Mark Zuckerberg era of moving fast and breaking things is over. A more socially aware society requires more from CEOs than ever before. Now, CEOs are not only expected to bring a value-driven product to market but to also consider the social implications of such a product. Here’s one question every CEO should be asking themselves.
I’ve lived and traveled extensively all over the world and rare are the metropolitan business ecosystems as vibrant and thriving as the one I’m living in now. I’ve witnessed how the confidence inspired by one, then two, then three successes in the ecosystem begins a virtuous cycle fueled by the resulting social confidence. I have a front row seat as I watch this confidence throwing off startup after startup after startup. It’s almost breathtaking right now.
Sometimes, and thankfully infrequently, that confidence might be more appropriately labeled as hubris. Hubris manifests itself as a disregard for the social impact of company strategy and its resulting choices. That is why when I recently read Hemant Taneja’s article in Harvard Business Review that exposed the need for more social awareness in the startup community, I slow-clapped alone in my office.
His article, The Era of “Move Fast and Break Things” Is Over empathically reminds us that the choices we make as we develop and roll out new products and companies do indeed have a social impact, irrespective of whether we’re aware. The primary concept he then elaborates on is the idea that Zuckerberg’s famous motto that companies should ‘move fast and break things’ was intended more to ‘inform the internal design and management processes rather than broadly applicable to building around and launching ideas without significant thought and testing.
The groundbreaking ideas we’re building new businesses around have increasingly significant social implications. Ideas such as artificial intelligence, genomics, blockchain, drones, AR/VR, 3D printing, etc are ideas that have far-reaching implications that we cannot toss about lightly.
Blackrock’s Chairman and CEO recently wrote a letter to CEOs that inspired both me and Teneja’s article. He is reminding some, and awakening in others, the idea that we as CEOs have a social responsibility. And that responsibility is growing. He suggested that:
“Unnerved by fundamental economic changes and the failure of government to provide lasting solutions, society is increasingly looking to companies, both public and private, to address pressing social and economic issues.”
The Big Question
When Taneja posed 8 questions that VCs should be asking companies, (and that frankly, all CEOs should be asking themselves) I read more closely than usual. They are great questions and CEOs that carefully consider their responses to the questions will be better prepared to create a positive social impact through their businesses.
Without reiterating the entire article, I’ll focus on what I believed to be the most important question, “What systemic, societal change do you aspire to create with your product?“
I’d suggest a small change for business owners, dreamers, CEOs, entrepreneurs, and starter-uppers alike: “What systemic, societal change do I aspire to create with my product?”
Taneja says,
“If a founder aspires to create a truly transformative tech company, they should appreciate the first, second, and third order possibilities of what that transformation means. When I ask entrepreneurs this question, I look for a sophisticated awareness of how other technologies, trends, and stakeholders map onto their vision for the future. More than anything, I look for empathy.
Let’s take a relatively simple example. Suppose we spoke to an entrepreneur working on human longevity. We would need to see a vision—and a minimum virtuous product—that addressed disruption in labor markets through automation (what does the world look like when people live longer and have less access to work?) and disparity in access (will society allow a world in which the wealthy live 2X as long as the middle class? 3X as long as the poor? Should it?). The best leaders of tomorrow will see these links and plan for them from day one.”
Now more than ever, CEOs need to be aware of the implications of their product and service on society as a whole, not just shareholders and customers. How does your product positively influence the ecosystem you live in? What about the negative implications? Spending time to ponder these questions will help CEOs build a more socially aware business ecosystem and allow them to thrive in a more socially-aware society. What would happen if we all considered these questions when determining the vision and mission of our business? I encourage all CEOs to read the full article and ask the same questions about your company and its purpose.
An Authentic and Humble Approach to Leadership
What is true leadership? Leadership isn’t fame, fortune, or even internal satisfaction. Rather, leadership is about creating a positive and lasting impact. Combined in a CEO, authenticity and humility are potent combinations for creating this impact.
Perhaps this more enlightened approach is why we’re seeing CEOs band together to talk about social impact as a primary driver of leadership. It was only 50 years ago that renowned University of Chicago economist Milton Friedman argued in the New York Times that “the social responsibility of a business is to increase its profits.” It seems we all got a little lost as we embraced that philosophy. I admit that I was convinced that they had it right, believing that all ultimately win if improving shareholder value is the primary motivator. It felt intuitive that investors won, but there is an argument that other key stakeholders won as well because business performance suffered if they were ignored. As a result, all benefited by keeping the focus on a lasting improvement to shareholder value.
Society tends to learn and adapt when it is led by great thinkers. The recent movement toward social impact has emerged as a result of leaders becoming more self-aware, humble, and authentic. Satya Nadella of Microsoft and Larry Fink of BlackRock are paving the way for making authenticity and consideration of others’ primary traits of leadership. Nadella argues for authenticity in his book “Hit Refresh”, which has been widely read among CEOs. Fink argues that, although increasing shareholder value isn’t a tired concept, perhaps we’re missing something if it is the sole focus of our efforts. He explains that profits are in no way inconsistent with purpose – in fact, they are inextricably linked .
The Friedman thinking is deeply embedded in business culture, however.
“The ideology of shareholder primacy has contributed to the economic inequality we see today in America…. the Chicago school of economics is so embedded in the psyche of investors and legal theory and the C.E.O. mind-set. Overcoming that won’t be easy.”
– Darren Walker, President of the Ford Foundation
This post is not solely about the drive toward social impact, but rather about the notion that leaders can see a better way through authenticity and humility. It is this expanded view of leadership that gives me hope as I envision CEOs realizing their need to understand themselves more deeply and comprehend their true motives. This takes a measure of humility to achieve because others often see us more clearly than we see ourselves; to accept their insights we need to be vulnerable and honest with ourselves. CEOs with these characteristics impress me the most, and I see them having a real and lasting impact in their organizations, whether they are crusading for a greater focus on social impact in the boardroom or for more empathy in the mail room. These are CEOs with the power to lead successful organizations and to change lives for good.